Buying a Jeep is exciting, but for most people, paying the full price upfront isn’t realistic. That’s where Jeep financing comes in.
You might wonder, “Who does Jeep finance through?” Understanding how Jeep financing works, which banks and lenders are involved, and what options you really have can help you make smarter choices.
This article explains Jeep’s financing partners, gives practical advice, and answers key questions—all in clear, easy-to-read English.
Who Handles Jeep Financing?
Jeep vehicles are financed mainly through Chrysler Capital. This lender is a partnership between FCA US LLC (Jeep’s parent company) and Santander Consumer USA. Chrysler Capital provides financing for new and used Jeep vehicles at dealerships across the US.
Other banks and credit unions also offer Jeep financing. Dealerships often work with a group of lenders, giving you several options. Here’s how it typically works:
- You choose a Jeep at the dealership.
- The dealer submits your application to Chrysler Capital and other lenders.
- You compare offers and choose the best one.
Some Jeep buyers prefer to arrange financing themselves, either through their own bank or a credit union. This is called direct lending.
Jeep’s Main Financing Partners
Chrysler Capital is the official lender for Jeep. But dealerships also work with other banks. Here’s a quick comparison of the most common Jeep financing partners:
| Lender | Type | Average APR (2024) | Key Features |
|---|---|---|---|
| Chrysler Capital | Captive (Jeep/FCA) | 3.5% – 6% | Special offers, lease deals, flexible terms |
| Bank of America | National Bank | 4% – 7% | Online pre-approval, competitive rates |
| Local Credit Unions | Member-owned | 3% – 5.5% | Lower rates, personalized service |
Chrysler Capital often has special promotions, such as 0% APR for certain Jeep models. However, credit unions frequently offer lower rates for qualified members. Bank of America and other national banks provide fast online applications but may not have the same incentives as Chrysler Capital.

Financing Options For Jeep Buyers
You have several ways to finance a Jeep:
- Dealer-arranged financing: The dealer submits your application to multiple lenders, including Chrysler Capital. This is the easiest option for most buyers.
- Direct lending: You get a loan from your bank or credit union before you shop. This gives you more control and often lower interest rates.
- Leasing: Instead of buying, you can lease a Jeep through Chrysler Capital or other lenders. Leasing means lower monthly payments but you don’t own the vehicle.
Here’s how these options stack up:
| Method | Ownership | Monthly Payment | Flexibility |
|---|---|---|---|
| Dealer Financing | Yes | Medium | Good (multiple lenders) |
| Direct Lending | Yes | Lower | High (pre-approval) |
| Leasing | No | Lowest | Limited (mileage, term) |
Many buyers overlook direct lending, but it can offer better rates and terms. Dealers may push their preferred lenders, but always ask for a comparison.
Jeep Incentives And Special Offers
Jeep often has special incentives for buyers. These can include:
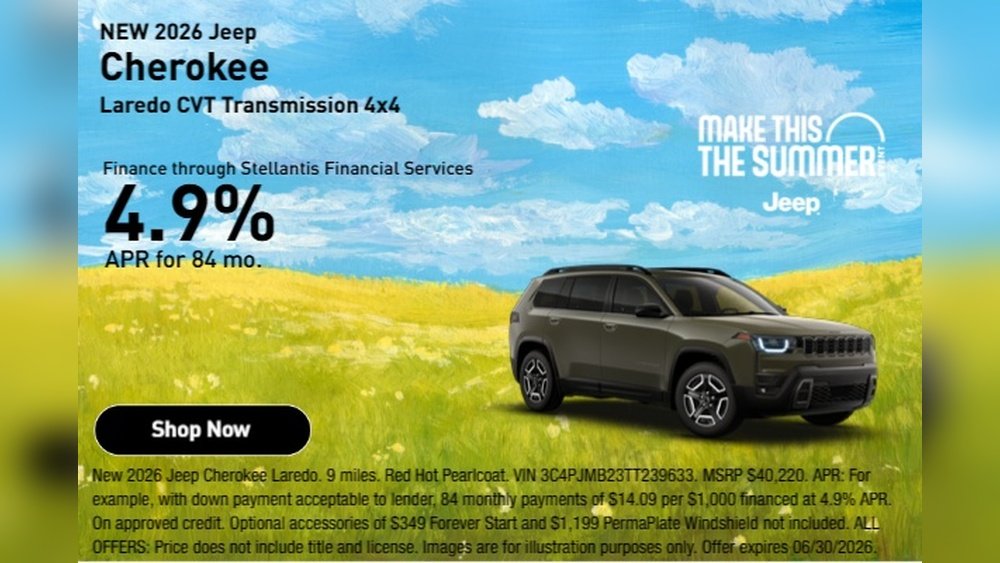
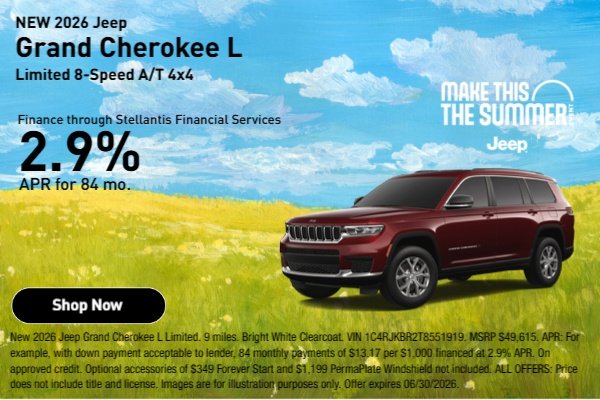
- 0% APR financing for 36 or 48 months
- Cash rebates ($1,000–$5,000)
- Lease deals with low monthly payments
These incentives are usually available through Chrysler Capital. To qualify, you need good credit (usually a score above 700).
If you don’t qualify, you may get higher rates or smaller rebates.
A non-obvious tip: incentives change monthly. Always check the Jeep website or ask your dealer about the latest offers. Sometimes, waiting just a few weeks can save you hundreds or even thousands of dollars.
What Really Matters When Choosing Jeep Financing
Choosing the right financing for your Jeep isn’t only about the interest rate. Here are the main factors:
- APR: The annual percentage rate affects your monthly payment and total cost.
- Loan term: Shorter terms mean higher payments but less interest overall.
- Down payment: A bigger down payment lowers your loan amount and could get you a better rate.
- Fees: Watch for hidden fees, like origination or prepayment penalties.
- Incentives: Special offers can make dealer financing more attractive.
A mistake many buyers make: focusing only on monthly payment. It’s smarter to look at the total cost over the life of the loan. Ask for a full breakdown before you sign.
How To Apply For Jeep Financing
Applying for Jeep financing is simple, but you should prepare:
- Check your credit score before visiting the dealer.
- Compare rates from Chrysler Capital, banks, and credit unions.
- Decide if you want to lease or buy.
- Gather documents: Income proof, ID, residence info.
Most dealerships submit your application electronically. You’ll usually get offers within an hour.
Don’t feel pressured—take your time to review each offer.
For more details about Chrysler Capital, visit the Chrysler Capital official site.
Frequently Asked Questions
Who Does Jeep Finance Through?
Jeep mainly finances through Chrysler Capital, but dealerships also work with banks and credit unions. You can choose the lender that offers the best terms.
Can I Finance A Jeep Through My Own Bank?
Yes, you can. This is called direct lending. You get a pre-approved loan from your bank or credit union and use it to buy your Jeep.
Is Leasing A Jeep Better Than Buying?
Leasing has lower monthly payments and lets you drive a new Jeep every few years. Buying costs more monthly but builds equity and gives you ownership. The best choice depends on your needs.
What Credit Score Is Needed For Jeep Financing?
Most lenders want a credit score of at least 650. For special offers or low rates, aim for 700 or higher.
Some loans have origination fees or prepayment penalties. Ask your dealer or lender for a list of all fees before signing.
Jeep financing can seem complex, but knowing who the real lenders are and what options you have makes it much easier. Remember to compare offers, check for incentives, and read the fine print.
With the right approach, you’ll drive away in your new Jeep with confidence.