Many car buyers ask if Jeep is offering 0 financing right now. Zero percent financing means you can borrow money for your new vehicle without paying any interest.
This can save you thousands of dollars over the loan period. However, these offers are not always available, and they may come with certain requirements.
If you’re thinking about buying a Jeep and want to know if you can get 0% financing, this article will guide you through the facts, current offers, and what you need to know before heading to the dealership.
What Is 0% Financing?
Zero percent financing is a special loan offer where you pay no interest on your car loan. For example, if you borrow $30,000 for a Jeep, you pay back only the $30,000 over the loan term, not a dollar more.
Most regular car loans charge interest, so this deal can save a lot of money.
But 0% financing is usually offered only to buyers with excellent credit scores. Also, not all models or trim levels are eligible. Sometimes, the offer is limited to a short period, such as during a holiday sale or model-year clearance.
Is Jeep Currently Offering 0% Financing?
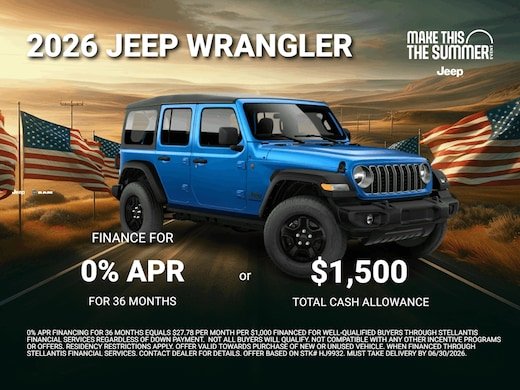
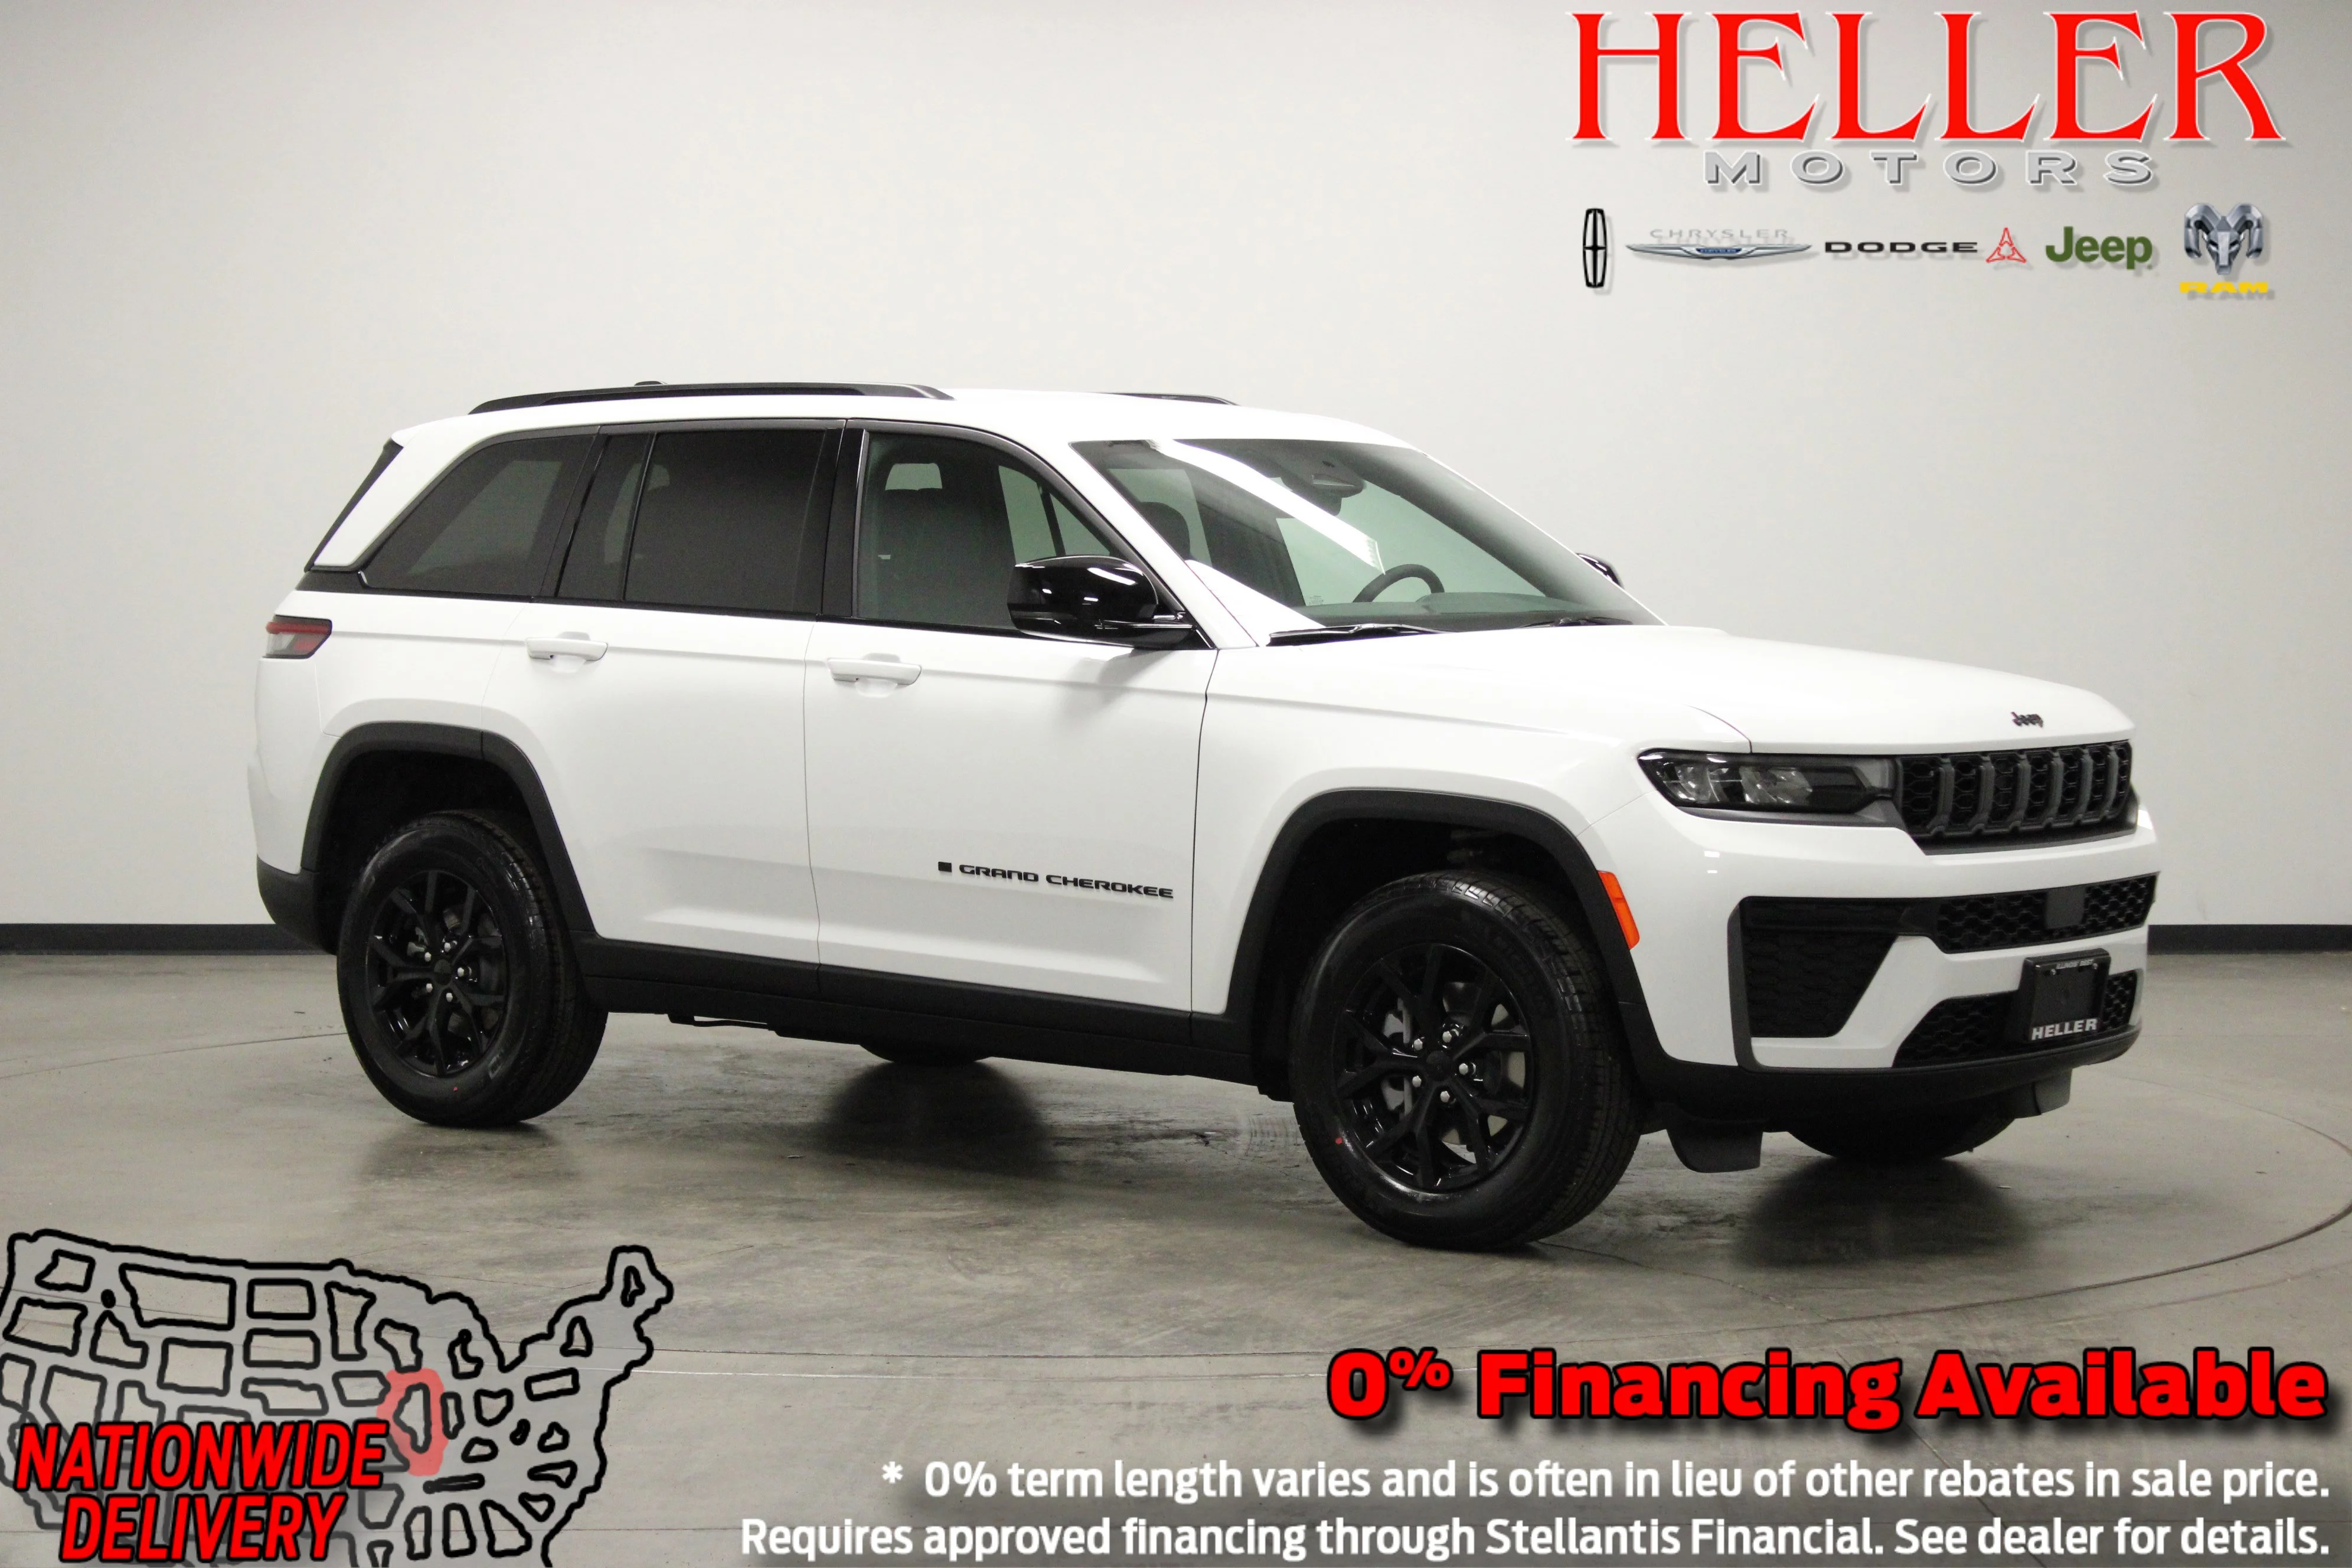
Jeep sometimes offers 0% financing on select models, but these deals are not always available. As of mid-2024, Jeep has provided special financing on popular models like the Jeep Grand Cherokee and Jeep Wrangler, but the exact terms can change each month.
Here’s a recent example of Jeep financing offers in the US:
| Model | APR Offer | Loan Term |
|---|---|---|
| 2024 Jeep Grand Cherokee | 0% for qualified buyers | 36 months |
| 2024 Jeep Wrangler | 0.9% for qualified buyers | 36 months |
| 2024 Jeep Compass | 1.9% for qualified buyers | 36 months |
These deals can be regional, so what’s available in your state might be different. Always check the official Jeep website or visit a local dealership for the latest information.
Who Qualifies For 0% Financing?
Jeep’s 0% financing offers are usually reserved for buyers with top-tier credit. This generally means a credit score of at least 720. The lender may also look at your income, debt level, and payment history.
If you have a lower credit score, you may still qualify for other low-interest offers, but probably not 0%. Dealers sometimes suggest a cash rebate or a special rate instead.
Comparing 0% Financing To Other Offers
Sometimes, Jeep will let you choose between 0% financing or a cash rebate. It’s important to understand which offer saves you more money. Here’s an example comparison:
| Offer Type | Loan Amount | Interest Rate | Monthly Payment (36 mo.) | Total Paid |
|---|---|---|---|---|
| 0% Financing | $30,000 | 0% | $833 | $30,000 |
| $2,000 Rebate + 4% APR | $28,000 | 4% | $824 | $29,664 |
As you can see, sometimes the rebate with a higher rate can be close in cost to 0% financing. Always ask your dealer to show you both options.
What To Watch Out For
Many buyers miss a few important details when considering 0% financing:
- Short loan terms: Most 0% deals are for 36 or 48 months, not 60 or 72. This means higher monthly payments.
- Limited to certain models: Not every Jeep model or trim is included.
- Fine print: Fees and taxes are not included in the 0% offer.
- No combination with other offers: You usually can’t combine 0% financing with other big discounts.
Dealers sometimes advertise “as low as 0% APR,” but this only applies to buyers with the best credit. Ask for the full terms in writing.
Practical Tips For Getting 0% Financing
If you want to qualify for Jeep’s 0% financing, consider these steps:
- Check your credit score before visiting the dealer. If your score is below 720, work on improving it first.
- Bring proof of income such as recent pay stubs or tax returns.
- Be flexible about models and trims. If you only want a specific color or package, you might miss the best deals.
- Negotiate the price first, then discuss financing. Sometimes, a dealer will try to focus only on the monthly payment.
- Read the contract carefully before signing. Make sure you understand all fees and the total loan amount.
Here’s a quick look at how much you could save with 0% financing compared to a standard loan:
| Loan Amount | Loan Term | Interest Rate | Total Interest Paid |
|---|---|---|---|
| $35,000 | 36 months | 0% | $0 |
| $35,000 | 36 months | 5% | $2,756 |
Is 0% Financing Always The Best Deal?
Not always. Sometimes, a large cash rebate or a dealer discount can be better than 0% financing. For example, if you plan to pay off your loan early, you might not save much with 0% financing over a rebate.
Also, some dealers raise the price of the car when you choose 0% financing. Always check the final sale price and compare it to other local offers.
Another insight: even if you get 0% financing, other costs like insurance and sales tax remain the same. Make sure you factor these into your budget.
Where To Find Current Jeep Financing Offers
The best place to find up-to-date offers is Jeep’s official website or your local Jeep dealer. You can also use trusted car shopping sites for more details. For a reliable source on car financing, visit Edmunds.
Frequently Asked Questions
What Credit Score Do I Need For Jeep 0% Financing?
You usually need a credit score of 720 or higher to qualify. Some lenders may have even stricter requirements.
Is 0% Financing Available For All Jeep Models?
No, 0% financing is often limited to select models and trim levels. Popular choices like the Grand Cherokee sometimes have this offer, but not always every version.
Can I Combine 0% Financing With Other Discounts Or Rebates?
Most of the time, you cannot combine 0% financing with cash rebates or other special deals. You need to choose one offer.
How Long Do Jeep’s 0% Financing Offers Last?
These offers are usually for a limited time, often 30 to 60 days. Always check the expiration date before making a decision.
What Happens If I Pay Off My 0% Loan Early?
There is usually no penalty for paying off a 0% loan early, but check your contract to be sure. You will not get any extra savings from early payoff since there is no interest.
Jeep’s 0% financing offers can be an excellent way to save money, but only if you qualify and the offer matches your needs. Always compare all available deals, read the fine print, and make sure you understand the total cost before signing.
This will help you drive away in your new Jeep with confidence and no financial surprises.