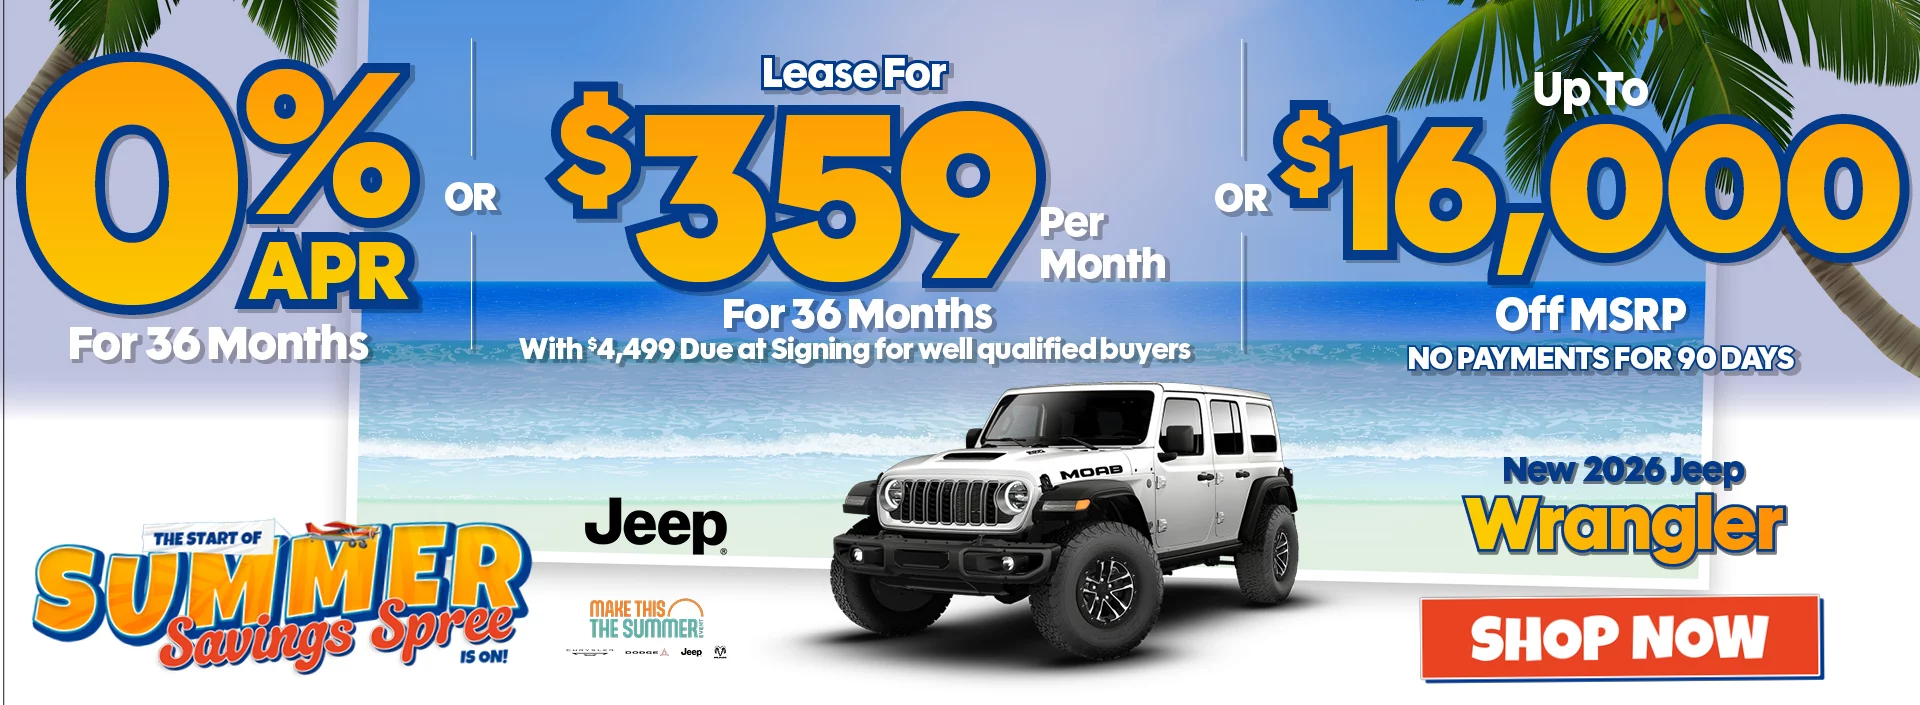
Shopping for a new vehicle is exciting, but understanding all the deals and offers can be confusing. If you’re considering a Jeep, you might wonder, “Does Jeep have 0% financing right now?”
This question matters because 0% financing can save thousands over the life of a car loan. Let’s break down what’s available, how these offers work, and what you should know before making your decision.
What Does 0% Financing Mean?
Zero percent financing is a special loan offer where you pay no interest on your auto loan. Normally, when you borrow money to buy a car, the bank or dealership charges interest. With 0% APR (Annual Percentage Rate), every payment goes directly to the price of the car, not to the lender’s profits.
This deal makes monthly payments lower and means you pay less overall. However, these offers are usually limited to buyers with excellent credit and may only apply to specific models or terms.
Is Jeep Offering 0% Financing Right Now?
Automotive incentives change often. As of mid-2024, Jeep does not have a universal 0% financing offer for all models, but selected deals may be available on certain vehicles or in special situations.
Jeep’s current promotions tend to focus on low APR offers rather than blanket 0% deals. For example, you might find 1.9% or 2.9% APR on popular models like the Jeep Grand Cherokee or Jeep Compass, especially for shorter loan terms (like 36 months).
Here’s a quick comparison of recent Jeep financing offers as of June 2024:
| Jeep Model | APR Offer | Loan Term (Months) |
|---|---|---|
| Jeep Wrangler | 2.9% APR | 36 |
| Jeep Grand Cherokee | 1.9% APR | 36 |
| Jeep Compass | 3.9% APR | 60 |
It’s important to note these offers can change monthly, and some regions may have different deals. Always check with your local Jeep dealer for the latest information.

Why 0% Financing Is Rare
Many people ask why 0% financing is not offered on every car. The answer is simple: 0% financing is expensive for Jeep and the lenders. They lose out on interest income and can only offer these deals when they need to clear inventory or boost sales on specific models.
Also, only buyers with top credit scores (usually above 700) are eligible. Lenders want to minimize risk with these promotions.
Here are some reasons Jeep may not always offer 0% financing:
- Interest rates are rising in the US, making it costly for automakers to subsidize 0% deals.
- High demand for certain Jeep models means there’s less need to offer big incentives.
- Inventory shortages can mean fewer promotions as dealers have less need to attract buyers.
How To Find The Best Jeep Financing Deal
If you’re looking for the lowest possible rate, it helps to be prepared. Here are some tips to help you get the best financing for your new Jeep:
- Check your credit score before shopping. Better credit means better offers.
- Compare offers from Jeep, banks, and credit unions. Sometimes, outside lenders offer lower rates.
- Negotiate the price of the vehicle before discussing financing. This way, you avoid hidden markups.
- Look for manufacturer incentives. Jeep sometimes offers bonus cash or special rates for qualified buyers.
- Shop at the end of the month or year. Dealers may have extra motivation to meet sales goals and offer better deals.
A quick look at how different APRs affect your payment:
| APR | Loan Amount | Monthly Payment (36 mo.) | Total Interest Paid |
|---|---|---|---|
| 0% | $35,000 | $972 | $0 |
| 1.9% | $35,000 | $1,010 | $366 |
| 2.9% | $35,000 | $1,025 | $900 |
As you can see, even a small difference in APR can add up over time.
What To Watch Out For
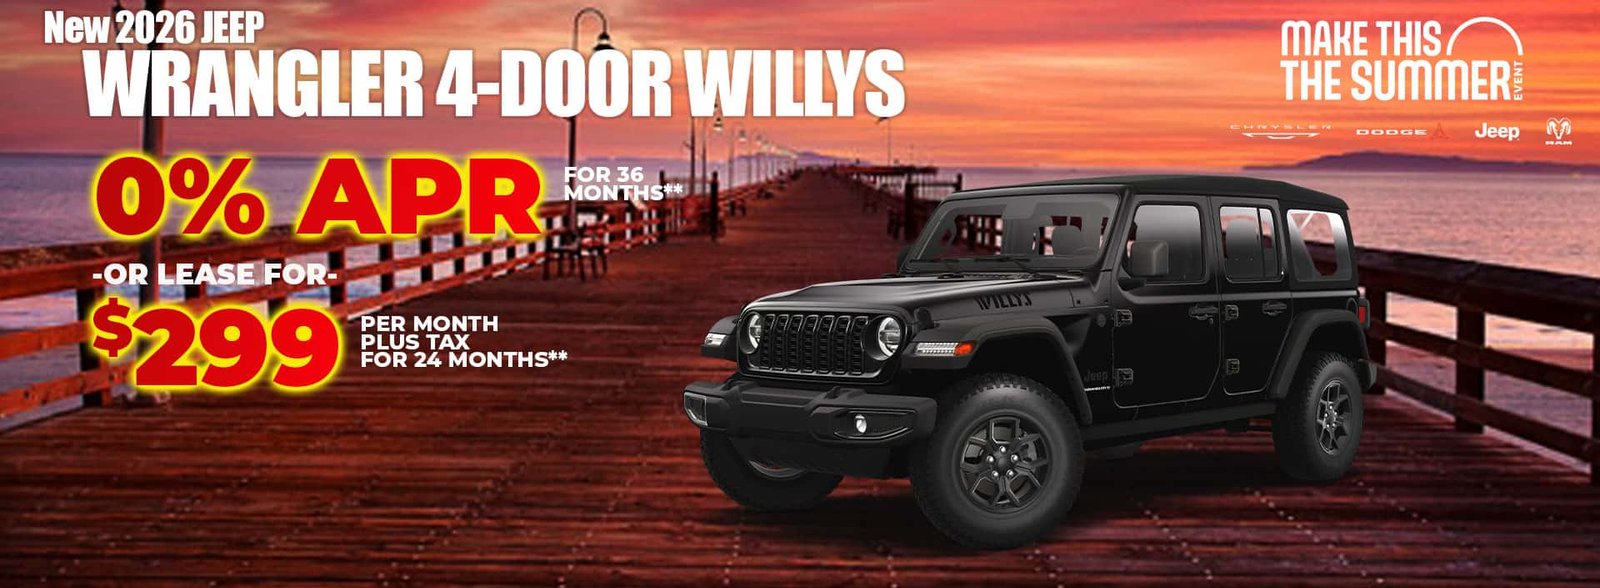
When you see 0% financing advertised, read the fine print carefully. Here are some common limitations and requirements:
- Short loan terms: 0% offers may only last for 36 months, which can make monthly payments higher.
- Down payment: You may need to put more money down to qualify.
- Model limitations: Not every Jeep model or trim will qualify.
- Credit requirements: Only those with excellent credit are eligible.
Also, sometimes cash rebates and 0% financing are not available together. You may have to choose one or the other.
Always do the math to see which deal saves you more money.
Should You Wait For A 0% Jeep Offer?
Timing can make a difference. Jeep sometimes releases special offers during holiday sales, model year-end clearances, or when launching new vehicles.
If you’re not in a rush, waiting for these events could help you catch a 0% financing deal.
But remember, waiting for the perfect deal has risks. Interest rates may rise, your credit score could change, or the car you want could sell out. If you find a deal that fits your budget and needs, it’s often smarter to act rather than wait for a slightly better offer.
Other Ways To Save On Your Next Jeep
If 0% financing is not available, there are still ways to save:
- Look for cash rebates: These can lower your purchase price right away.
- Consider leasing: Sometimes lease specials offer lower monthly payments.
- Trade-in incentives: Dealers may offer more for your old vehicle during special promotions.
- Certified Pre-Owned (CPO) programs: CPO Jeeps often come with lower rates and extra benefits.
Here’s a comparison between Jeep financing and leasing:
| Option | Average Monthly Cost | Ownership | Best For |
|---|---|---|---|
| Financing (60 mo.) | $600–$800 | Yes, after loan | Long-term use, high mileage |
| Leasing (36 mo.) | $350–$500 | No | Short-term, low mileage |
Frequently Asked Questions