Buying a new car is exciting, but understanding the financing options can feel confusing. Many Jeep shoppers wonder if the brand offers zero percent financing. This type of deal means you pay no interest on your auto loan, which can save thousands of dollars over the life of the loan. Let’s explore if Jeep offers zero percent financing, how it works, and what you need to know before making your decision.
What Is Zero Percent Financing?
Zero percent financing is a special offer where the borrower pays no interest on their car loan. For example, if you finance a $30,000 Jeep at zero percent for 60 months, you pay only $30,000 total, not a penny more. Usually, car loans charge interest, so zero percent deals are valuable.
These offers are typically available for new vehicles, not used cars. Automakers use zero percent financing to attract buyers and boost sales of certain models, especially when new versions are coming or inventory is high.
Does Jeep Offer Zero Percent Financing?
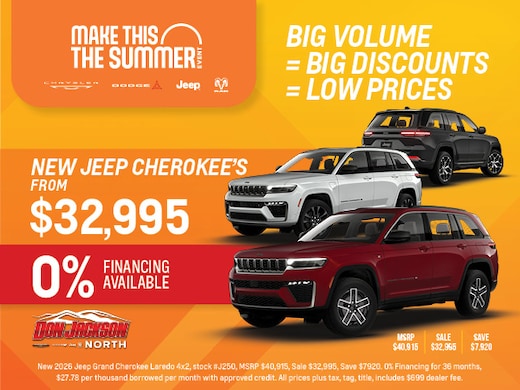
Jeep sometimes offers zero percent financing, but not all the time or for every model. The deals depend on factors like the model year, dealer inventory, and current promotions.
For example, in early 2024, Jeep offered zero percent APR for 36 months on select models such as the Jeep Grand Cherokee and Jeep Compass. However, not every dealership or region had the same offers. These promotions are usually announced on the official Jeep website or through local dealerships.
Here’s a quick overview of recent Jeep financing offers:
| Jeep Model | Zero Percent Financing | Offer Duration |
|---|---|---|
| Grand Cherokee | Yes | 36 months |
| Compass | Yes | 36 months |
| Wrangler | No | N/A |
| Renegade | No | N/A |
Keep in mind, these deals change often. Always check with your local Jeep dealer for the latest financing offers.
How To Qualify For Zero Percent Financing
Zero percent financing is attractive, but not everyone can qualify. Jeep and its financing partners usually require:
- Excellent credit score: Most deals require a score of 700 or higher.
- Proof of income: You must show you can afford the monthly payments.
- Low debt-to-income ratio: Lenders want to see you have manageable debts.
- Down payment: Sometimes a down payment is needed, though not always.
If your credit score is lower, you may be offered a higher interest rate. Here’s how credit score affects Jeep financing:
| Credit Score Range | Likely APR | Zero Percent Eligibility |
|---|---|---|
| 750+ | 0% – 2.9% | High |
| 700–749 | 2.9% – 4.9% | Possible |
| 650–699 | 4.9% – 7.9% | Low |
| Below 650 | 7.9%+ | Unlikely |
Tip: Check your credit score before visiting the dealership. If your score is not high enough, you can improve it by paying off debts and making payments on time.
Comparing Zero Percent Financing To Other Offers
Sometimes Jeep dealers offer cash rebates or special lease deals instead of zero percent financing. It’s important to compare these offers to see which saves you more money.
Let’s look at an example:
| Option | Monthly Payment | Total Interest | Cash Savings |
|---|---|---|---|
| Zero Percent Financing (60 months) | $500 | $0 | $0 |
| Standard Financing (3.9% APR, 60 months) | $550 | $3,000 | $0 |
| Cash Rebate ($2,000 off, 3.9% APR, 60 months) | $515 | $2,500 | $2,000 |
Sometimes, a cash rebate saves more than zero percent financing, depending on your loan amount and term. Always ask the dealer to show you the total cost for each option.

What Most Buyers Miss
Many buyers focus only on the interest rate. But here are two things beginners often miss:
- Hidden fees: Even with zero percent financing, dealers may charge fees like documentation, loan origination, or extended warranties. Ask for a full breakdown before signing.
- Limited models and terms: Not every Jeep model or trim gets zero percent. Often, it’s only for popular or outgoing models, and the term may be shorter than standard loans.
Another tip: Zero percent financing sometimes requires you to give up other offers, like cash rebates. Always ask if combining deals is possible, or if you must choose one.
Where To Find Jeep Financing Offers
The best place to check for current Jeep financing deals is the official Jeep website or your local dealership’s website. National offers are listed online, but local dealers may have extra incentives.
For more detailed information on auto financing, you can also visit Consumer Reports.
Frequently Asked Questions
What Does Zero Percent Financing Mean For Jeep Buyers?
It means you pay no interest on your auto loan, so the total repayment equals the vehicle’s price. This can save you money compared to regular loans.
Can I Get Zero Percent Financing With Bad Credit?
Usually, no. Jeep zero percent offers are mainly for buyers with excellent credit scores. If your score is low, you will likely get a higher interest rate.
Are Zero Percent Deals Available For Used Jeeps?
No, these offers are only for new Jeep vehicles. Used Jeeps do not qualify for zero percent financing from the manufacturer.
How Often Does Jeep Offer Zero Percent Financing?
Jeep offers these deals during special promotions, often at the end of the model year or during big sales events. They are not available year-round.
Is Zero Percent Financing Better Than Cash Rebates?
It depends on your situation. Sometimes a cash rebate gives more savings, especially if you plan to pay off the loan quickly. Compare both options before deciding.
Zero percent financing is a great way to save on your new Jeep, but it’s not always available or the best fit for every buyer. Check your credit, compare all offers, and ask the dealer for clear details.
That way, you can make the best financial choice for your next adventure.