Is Jeep Doing 0 Financing?
Buying a new car can feel confusing, especially when you see terms like 0 financing everywhere. If you’re thinking about a Jeep, you might wonder if this deal is real or just marketing.
Let’s break down what zero percent financing means, if Jeep offers it, and how to know if it’s right for you. You’ll get clear facts, real numbers, and practical tips—all in simple English.
What Is 0 Financing?
Zero percent financing is a special deal from car makers or dealers. It means you pay no interest on your loan. If you borrow $30,000 for a Jeep, you only pay back $30,000—no extra fees. Usually, car loans have interest rates between 2% and 6%. With zero percent, you save a lot.
But there are rules. Not everyone can get 0% financing. You often need:
- Excellent credit score (usually above 700)
- Buy a new Jeep, not used
- Go through Jeep’s own finance company
So, while zero percent sounds great, it’s not for everyone.
Is Jeep Offering 0 Financing Right Now?
Jeep sometimes gives 0 financing deals, but not all the time. These offers change based on:
- Season (more deals in spring and year-end)
- Model (some Jeeps, like the Wrangler, may not qualify)
- Location (offers can differ by state)
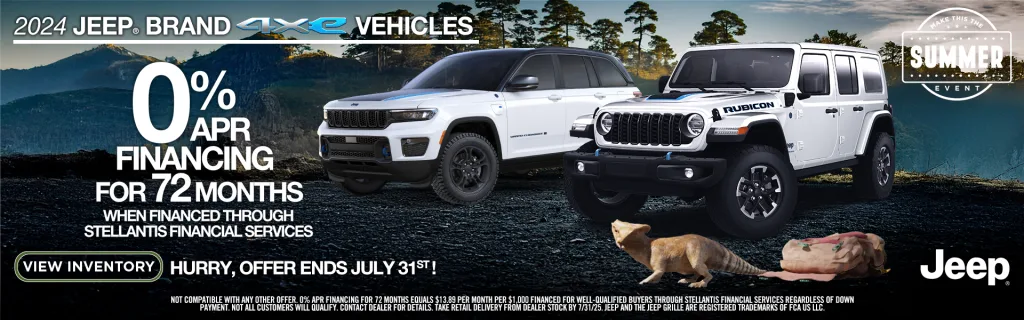
As of June 2024, Jeep is offering 0% financing on select models, like the Jeep Grand Cherokee and Jeep Compass. But the deals can end fast or only last a few weeks.
Here’s a simple comparison of Jeep models and their current financing rates:
| Jeep Model | Typical Financing Rate | 0% Financing Available? |
|---|---|---|
| Jeep Grand Cherokee | 0% – 3.49% | Yes (Limited Time) |
| Jeep Compass | 0% – 4.99% | Yes |
| Jeep Wrangler | 2.99% – 6.99% | No |
| Jeep Renegade | 1.99% – 5.99% | Rarely |
Always check Jeep’s official site or your local dealer for the latest updates.
How Does 0 Financing Work?
If you qualify, Jeep’s 0% financing works like this:
- You buy a new Jeep.
- You finance through Chrysler Capital or Jeep’s partner banks.
- You pay monthly installments—no extra interest.
Let’s see how much you can save compared to a standard loan.
| Loan Amount | Term (Months) | Interest Rate | Total Paid |
|---|---|---|---|
| $30,000 | 60 | 0% | $30,000 |
| $30,000 | 60 | 3.5% | $32,768 |
| $30,000 | 60 | 5% | $34,787 |
With 0%, you save $2,768 $4,787 over five years.
Who Can Qualify For Jeep’s 0 Financing?
To get Jeep’s zero percent financing, you need:
- Strong credit history (score above 700)
- Stable income and low debts
- Buy a new Jeep (not certified pre-owned)
- Sometimes, a larger down payment
Some buyers miss the fact that even if you have good credit, Jeep may check your debt-to-income ratio. If you owe too much elsewhere, you may not qualify.
Another tip: Dealers sometimes push other incentives if you don’t qualify for 0%. For example, cash back or lower rates. Always ask for all available offers.
Is 0 Financing Always The Best Deal?
Many buyers think 0 financing is always the smartest choice. But that’s not always true. Sometimes, Jeep offers a cash rebate if you take a higher interest rate. For example:
- 0% financing OR $3,000 cash back with 3.99% financing
If you have the cash and plan to pay off your loan quickly, the cash back might be better. Always compare both options.
Here’s a quick comparison:
| Offer | Loan Amount | Interest Rate | Cash Back | Total Paid |
|---|---|---|---|---|
| 0% Financing | $30,000 | 0% | $0 | $30,000 |
| Cash Back Offer | $27,000 | 3.99% | $3,000 | $29,798 |
In this example, the cash back deal saves more if you qualify.
Common Mistakes To Avoid
- Assuming all Jeeps have 0% financing. It’s only for select models and buyers.
- Ignoring hidden fees. Some dealers add extra charges, so check the final price.
- Not comparing offers. Sometimes, rebates are better than 0% interest.
- Missing credit requirements. If your credit score is too low, you might waste time applying.
- Not reading the fine print. Offers can have restrictions, like short loan terms or limited locations.
Many buyers overlook the importance of pre-approval from their own bank. Sometimes, outside lenders offer better deals than Jeep’s own financing.
How To Get The Best Jeep Financing Deal
If you’re serious about buying a Jeep, follow these steps:
- Check your credit score first.
- Ask your local dealer about all current offers.
- Compare 0% financing with cash rebates and standard rates.
- Get pre-approved from your own bank or credit union.
- Read every document before signing.
You can also visit the official Jeep website or trusted sources like Edmunds for up-to-date deals and reviews.
Frequently Asked Questions
What Does 0 Financing Mean For Jeep Buyers?
It means you pay no interest on your loan. Your monthly payments only cover the Jeep’s price, not extra fees.
Can I Get 0% Financing On A Used Jeep?
No. Zero percent financing is only for new Jeeps. Used Jeeps usually have higher rates.
What Credit Score Do I Need For Jeep’s 0 Financing?
Usually, you need a score of 700 or higher. Some lenders may accept slightly lower, but your chances drop.
Sometimes, dealers add processing or documentation fees. Always check the final contract to be sure.
Should I Choose 0 Financing Or A Cash Rebate?
Compare both options. Sometimes, the cash rebate saves more money, especially if you pay off the loan early.
Jeep’s 0 financing offers can be a smart way to save, but only if you qualify and read the details. Check your credit, compare offers, and never rush into a deal.
With careful planning, you’ll drive home your new Jeep knowing you got the best value.